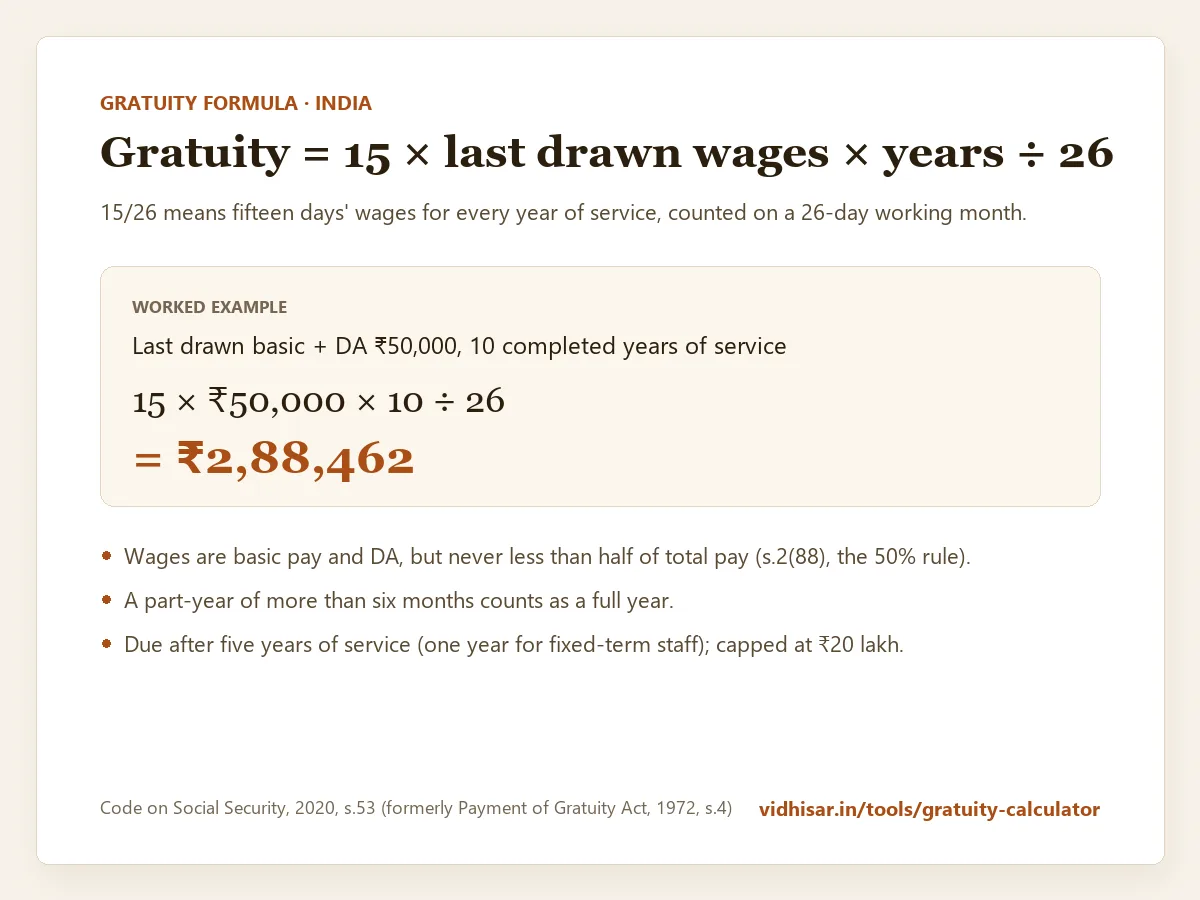
Calculate gratuity under the new labour code: fifteen days of wages per year on a twenty-six day month, the 50% wage rule, fixed-term gratuity after one year, capped at ₹20 lakh.
Quick Statutory Answer
Since 21 November 2025, gratuity is governed by Section 53 of the Code on Social Security, 2020, which replaced the Payment of Gratuity Act 1972. The formula is unchanged: 15 days of last drawn wages for every completed year of service, on a 26-day month — (15 × wages × years) ÷ 26. Wages now follow the Code's definition, so if allowances exceed half of total pay the excess is added back. Regular employees qualify after 5 years of continuous service, fixed-term employees after 1 year (paid pro rata), and the ceiling remains ₹20,00,000.
Worked example
For an employee whose last drawn basic plus dearness allowance was ₹50,000, with 10 completed years of service: 15 × ₹50,000 × 10 ÷ 26 = ₹2,88,462. Under the Code on Social Security, wages cannot be less than half of total pay: on a ₹1,00,000 monthly package with ₹30,000 basic and DA, gratuity is worked on ₹50,000, giving ₹2,88,462 for the same 10 years.
Common questions
How is gratuity calculated in India?
Under section 53 of the Code on Social Security, 2020 — which replaced the Payment of Gratuity Act on 21 November 2025 — the formula is fifteen days of wages for every completed year of service, on a twenty-six day month: (15 × last drawn wages × years of service) ÷ 26. Wages means basic plus dearness allowance (and any retaining allowance), topped up if allowances exceed half of total pay, and a part-year over six months is counted as a full year.
Is the Payment of Gratuity Act, 1972 still in force?
No. Section 164 of the Code on Social Security, 2020 repealed it, and the Code came into force on 21 November 2025. The formula, the five-year rule for regular employees and the ₹20 lakh ceiling carried over. What changed is the wider definition of wages and gratuity for fixed-term employees after one year. The Labour Ministry's FAQ says gratuity falling due on or after 21 November 2025 is paid under the Code on the wages last drawn at exit, including for service before that date.
What is the 50% wage rule for gratuity?
Section 2(88) of the Code defines wages as basic pay, dearness allowance and retaining allowance, and leaves out items such as HRA, conveyance, overtime and commission. But if the left-out items add up to more than half of total remuneration, the excess is treated as wages. On a ₹1,00,000 monthly package with ₹30,000 basic and DA, gratuity is worked on ₹50,000, not ₹30,000.
What is the minimum service for gratuity?
Five years of continuous service for a regular employee. It does not apply where employment ends because of the employee's death or disablement. A fixed-term employee qualifies after one year of service under the contract, according to the Labour Ministry's FAQ of 16 March 2026, and is paid pro rata.
What is the maximum gratuity payable?
₹20,00,000. Section 53(3) caps it at the amount the Central Government notifies, and the Labour Ministry confirmed in December 2025 that this is currently ₹20 lakh. An employer is free to pay more as a contractual benefit.
When must gratuity be paid?
Within 30 days of it becoming payable, under section 56(3) of the Code on Social Security. If the employer does not pay in that period, section 56(4) makes it liable for simple interest from the date the gratuity became payable.
How is gratuity calculated in days?
The Code on Social Security calculates entitlement per year, not per day. Each completed year of service earns fifteen days of wages. For a monthly-paid employee, the daily wage equivalent is last drawn basic+DA divided by 26 (the statutory working-day month), and fifteen such days per year gives the formula (15 × wages × years) ÷ 26.
How many months of salary is gratuity?
Approximately half a month's wages per year of service — fifteen days out of twenty-six working days is about 57.7% of a month. For ten years of service the gratuity works out to roughly 5.77 months of basic plus DA, subject to the Rs 20 lakh cap. The exact formula is (15 × wages × years) ÷ 26.
How is gratuity calculated in months?
Service years are counted in completed years, with a part-year of more than six months rounding up to a full year. The gratuity amount is fifteen days of wages per year — which translates to approximately 0.577 months of basic+DA per year of service. The formula is (15 × last drawn wages × counted years) ÷ 26.
Maintained by the VidhiSar Legal Team
Maintains the law explainers, calculators, templates and blog posts on vidhisar.in: checks them against the statute text and updates them when the law changes. Errors and changes in the law can be reported to legal@vidhisar.in.