Employment · Template

Full and final settlement (F&F) statement format — India

The full and final settlement is where an exit either closes cleanly or turns into a claim. It is an arithmetic document, and there are statutory floors under the arithmetic: gratuity has its own formula and its own deadline, leave encashment follows the leave actually accrued, and the clock on paying the whole thing starts on the last working day whether or not anyone is watching it.

Quick Statutory Answer

How long do I have to pay a full and final settlement? Two working days for the wages. Section 17(2) of the Code on Wages, 2019 requires the wages of a departing employee to be paid within two working days of leaving, and it names resignation alongside dismissal, retrenchment and closure. Gratuity carries its own deadline: under section 56 of the Code on Social Security, 2020 the employer must arrange payment within thirty days of it becoming payable, with interest running on delay. Plan on days, not months.

Draft this document See all 30 templates

Full & Final Settlement Statement format

The full text of this document as VidhiSar drafts it, with every blank shown in square brackets. Copy it or download it as a Word file and fill it in yourself — or answer a few questions and VidhiSar fills it in and prints a formatted PDF. Clauses that apply only in some cases are left out here; the drafting flow adds them when your answers call for them.

STATEMENT DETAILS

Date: [Statement Date]

Employee: [Employee's Full Name] Employee Code: [Employee Code / ID] Designation: [Designation at Separation] Date of Joining: [Date of Joining] Last Working Date: [Last Working Date] Issued by: [Company Legal Name]

Subject: Statement of Full and Final Settlement of Account

EARNINGS

1. Unpaid Salary. Salary for [Unpaid Days Worked in Final Month] day(s) worked in the final month and not yet disbursed: Rs. [Unpaid Salary].

2. Leave Encashment. Encashment of [Leave Days Being Encashed] day(s) of accumulated leave standing to the employee's credit as at the last working date: Rs. [Leave Encashment].

3. Gratuity. Gratuity payable under section 53 of the Code on Social Security, 2020, computed at fifteen days' wages on last drawn wages for each completed year of continuous service and part thereof in excess of six months: Rs. [Gratuity Payable]. Where the employee has not completed the qualifying period of continuous service, this amount is recorded as Nil.

4. Bonus, Incentive and Reimbursements. Statutory bonus, performance incentive and approved expense reimbursements outstanding as at the last working date: Rs. [Bonus / Incentive / Reimbursements].

DEDUCTIONS

5. Notice Period Recovery. Recovery in respect of the unserved portion of the notice period, as provided in the employee's contract of employment: Rs. [Notice Period Recovery].

6. Other Recoveries. Advances, loans, asset non-return charges and other amounts lawfully recoverable: Rs. [Other Recoveries].

7. Tax Deducted at Source. Tax deducted at source under the Income-tax Act, 2025 on the taxable component of this settlement: Rs. [Tax Deducted at Source].

NET SETTLEMENT

8. Net Amount Payable. The net amount payable to the employee on full and final settlement is Rs. [Net Amount Payable], to be remitted by [Payment Mode] on or before [Payment Date]. The wages included in it fall due within two working days of the last working date under section 17(2) of the Code on Wages, 2019, and gratuity within thirty days of it becoming payable under section 56 of the Code on Social Security, 2020.

9. Statutory Fund Balances. Balances standing to the employee's credit in the provident fund and any other statutory fund are held by the respective statutory authority and are not part of this settlement. They are to be withdrawn or transferred by the employee directly with that authority, and the Company shall complete its part of the formalities on request.

10. Certificate of Tax Deducted. A certificate of tax deducted at source in the prescribed form shall be issued to the employee for the relevant tax year within the timeline prescribed under the Income-tax Act, 2025 and the rules made under it.

11. Basis of Statement. This statement has been prepared on the records available to the Company as at the date of issue. Any arithmetical error or omission notified by the employee in writing within thirty (30) days shall be examined and, if established, corrected and settled.

ACKNOWLEDGEMENT

For [Company Legal Name]

[Authorised Signatory Name] Authorised Signatory

Received the sum stated at Clause 8 in full and final settlement of all my claims arising out of my employment with the Company, subject to Clause 11 above.
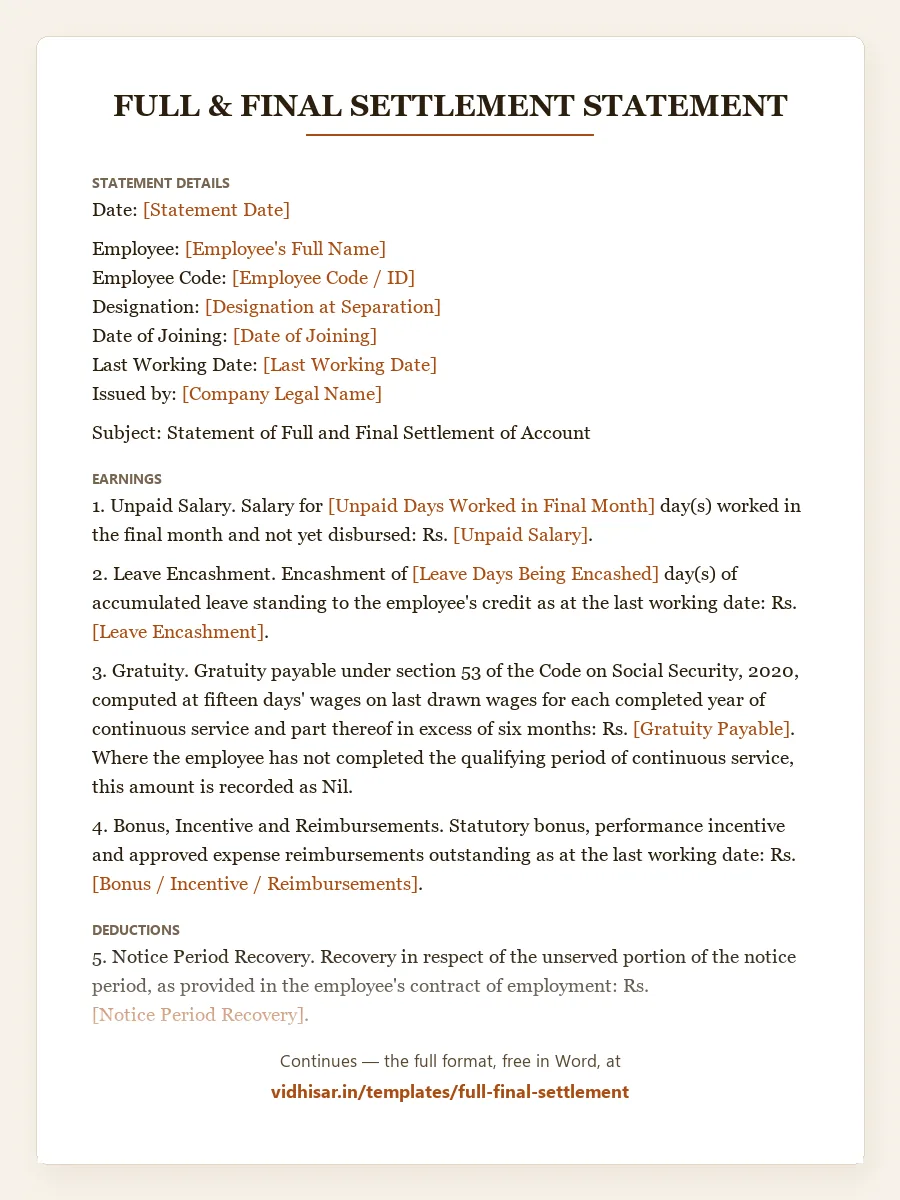
Full & Final Settlement Statement format (India): page one of the document, with each blank to fill in shown in brackets

The provision behind this document

  • Section 17, Code on Wages, 2019 — Monthly wages before the expiry of the 7th of the next month, daily, weekly and fortnightly limits, and wages due on an exit within two working days.
  • Section 53, Code on Social Security, 2020 — Five years' service (none for death, disablement or the end of a fixed term), fifteen days' wages a year on a 26-day month, a notified cap, and when gratuity can be forfeited.
  • Section 53, Code on Social Security, 2020 — Gratuity moved to s.53 of the Code on Social Security on 21 November 2025: the same 15/26 formula and ₹20 lakh cap, wider wages, and fixed-term staff after one year.

Further reading

What the law behind this document actually requires.

  • Full and final settlement: what you owe a departing employee, and when — Two working days for wages, thirty for gratuity. The deadlines are statutory, and "we settle at the end of the quarter" is not one of them.

Related statutory compliance tools & calculators

  • Gratuity Calculator India — Calculate statutory 15/26 gratuity under the Code on Social Security, 2020

What this document must contain (Clause-by-Clause Matrix)

Full & Final Settlement Statement — Mandatory Clause Matrix & Statutory Protection (2026)
Essential Clause Legal Purpose & Protection Governing Law / Benchmark
Every earning on its own line Unpaid salary days, leave encashment, gratuity, bonus, reimbursements. A single net figure is impossible for the employee to verify, and an unverifiable number is what turns a routine exit into a dispute. Code on Social Security, 2020 — ss. 53 and 56
Leave encashment computed on the leave actually standing to credit State the number of days being encashed, not just the amount. The balance is a fact the employee can check against their own record, and disagreements surface faster when both are shown. Code on Wages, 2019 — s. 17(2)
Gratuity shown separately, with the service period it rests on Gratuity is a statutory entitlement with its own computation, not a discretionary component of a package. Burying it inside a lump sum makes it look like a favour and makes the calculation impossible to audit. Income-tax Act, 2025
Deductions itemised, each pointing at its contractual basis A notice-period recovery has to be traceable to the clause that permits it and to the salary base that clause names. A deduction with no stated basis is the line that gets challenged first. Code on Social Security, 2020 — ss. 53 and 56
Tax deducted at source shown, and the certificate promised The components of an exit payment are not taxed alike. Showing the deduction and committing to issue the certificate for the relevant year prevents the query that otherwise arrives at return-filing time. Code on Wages, 2019 — s. 17(2)
A statement that statutory fund balances are not part of this settlement Provident fund and similar balances sit with the authority, and the employee withdraws or transfers them directly. Saying so stops the employee assuming those amounts were meant to be inside your figure. Income-tax Act, 2025
The payment date and mode, and a window to flag an arithmetic error A stated date makes the obligation checkable. A short correction window costs you nothing and converts most disagreements into a recalculation instead of a claim. Code on Social Security, 2020 — ss. 53 and 56
  • Every earning on its own line — Unpaid salary days, leave encashment, gratuity, bonus, reimbursements. A single net figure is impossible for the employee to verify, and an unverifiable number is what turns a routine exit into a dispute.
  • Leave encashment computed on the leave actually standing to credit — State the number of days being encashed, not just the amount. The balance is a fact the employee can check against their own record, and disagreements surface faster when both are shown.
  • Gratuity shown separately, with the service period it rests on — Gratuity is a statutory entitlement with its own computation, not a discretionary component of a package. Burying it inside a lump sum makes it look like a favour and makes the calculation impossible to audit.
  • Deductions itemised, each pointing at its contractual basis — A notice-period recovery has to be traceable to the clause that permits it and to the salary base that clause names. A deduction with no stated basis is the line that gets challenged first.
  • Tax deducted at source shown, and the certificate promised — The components of an exit payment are not taxed alike. Showing the deduction and committing to issue the certificate for the relevant year prevents the query that otherwise arrives at return-filing time.
  • A statement that statutory fund balances are not part of this settlement — Provident fund and similar balances sit with the authority, and the employee withdraws or transfers them directly. Saying so stops the employee assuming those amounts were meant to be inside your figure.
  • The payment date and mode, and a window to flag an arithmetic error — A stated date makes the obligation checkable. A short correction window costs you nothing and converts most disagreements into a recalculation instead of a claim.

When you need this

  • When an employee resigns, is terminated, retires or is retrenched
  • Alongside the relieving letter, so the person leaves with the number and the letter at the same time
  • When notice was short-served and you intend to recover the balance
  • When gratuity has become payable and has to be computed and released to a deadline
  • When a former employee has disputed what they were paid and you need to show the working

The law that governs it

  • Code on Social Security, 2020 — ss. 53 and 56 — Gratuity is payable on the termination of employment after five years of continuous service, a condition that does not apply on death, disablement or the expiry of a fixed-term contract. It is computed at fifteen days’ wages for each completed year of service on the last drawn wages, with wages as the Code defines them. The employer must determine the amount and pay it within thirty days of it becoming payable, and interest runs on a delayed payment. The ceiling is notified centrally, currently ₹20 lakh.
  • Code on Wages, 2019 — s. 17(2) — The wages of an employee who has been removed, dismissed or retrenched, who has resigned, or who lost their job because the establishment closed, must be paid within two working days of leaving. Resignation is named in the section, so the rule is not limited to terminations. The clock starts on its own: it does not wait for the next payroll run, a clearance form or a signed discharge. The Code replaced the Payment of Wages Act, 1936 on 21 November 2025.
  • Income-tax Act, 2025 — The components of a settlement are not taxed alike: gratuity and leave encashment carry their own exemptions with their own limits and conditions, and the remainder is salary. Deduct on the taxable portion and issue the certificate of tax deducted for the relevant tax year. The 2025 Act replaced the Income-tax Act, 1961 from 1 April 2026; a settlement paid before that date fell under the 1961 Act.

Common mistakes

  • Netting everything into one figure, so the employee cannot check it and assumes the worst about the parts they cannot see
  • Treating gratuity as negotiable, or as something to be set off against an unrelated grievance
  • Holding the settlement hostage to a signed discharge, when the statutory dues inside it were payable regardless
  • Recovering notice pay on gross salary where the contract says basic — or on no stated basis at all
  • Forgetting the certificate of tax deducted, which resurfaces months later when the employee cannot file their return

Frequently asked questions

How long do I have to pay a full and final settlement?

Two working days for the wages. Section 17(2) of the Code on Wages, 2019 requires the wages of a departing employee to be paid within two working days of leaving, and it names resignation alongside dismissal, retrenchment and closure. Gratuity carries its own deadline: under section 56 of the Code on Social Security, 2020 the employer must arrange payment within thirty days of it becoming payable, with interest running on delay. Plan on days, not months.

Can I adjust a notice-period shortfall against the settlement?

Where the contract provides for recovery and states the basis of calculation, yes — it is a contractual adjustment. What you cannot do is treat every payable as fungible: a statutory entitlement such as gratuity stands on its own footing and is not simply netted off against a contractual claim.

Is gratuity payable if the employee did not complete five years?

The qualifying period is five years of continuous service, and that condition does not apply where the employment ends on death or disablement. Some High Courts have taken a view on what counts as a completed year in the final year of service, so a borderline case is worth checking rather than deciding from the bare figure.

Does signing the settlement stop the employee from claiming later?

An acknowledgement of receipt is evidence, not an absolute bar. Statutory entitlements cannot be contracted away, and a discharge obtained under pressure can be challenged. The protection comes from the arithmetic being right and visible, not from the signature at the bottom.

Maintained by the VidhiSar Legal Team

Maintains the law explainers, calculators, templates and blog posts on vidhisar.in: checks them against the statute text and updates them when the law changes. Errors and changes in the law can be reported to legal@vidhisar.in.