Fundraise & governance · Template

Non-binding term sheet template for India

A term sheet is mostly non-binding, which is exactly why founders sign them too quickly. The economics and control terms it sets become the starting point of the definitive documents, and almost nothing agreed here gets walked back later. A few clauses are binding regardless — and those are the ones to read hardest.

Quick Statutory Answer

Is a term sheet legally binding in India? Usually the commercial terms are expressed to be non-binding, while specific clauses — confidentiality, exclusivity or no-shop, and costs — are binding. What matters is what the document itself says, so the binding provisions should be identified expressly rather than inferred.

Draft this document See all 30 templates

Non-Binding Term Sheet format

The full text of this document as VidhiSar drafts it, with every blank shown in square brackets. Copy it or download it as a Word file and fill it in yourself — or answer a few questions and VidhiSar fills it in and prints a formatted PDF. Clauses that apply only in some cases are left out here; the drafting flow adds them when your answers call for them.

TERM SHEET — NON-BINDING

Date: [Date of Term Sheet]

This Term Sheet sets out the non-binding principal terms on which [Investor Name] ("Investor") proposes to invest in [Company Name], having its registered office at [Company Registered Address] ("Company"). This Term Sheet is not legally binding (save for the Confidentiality, Exclusivity, and Governing Law provisions below) and is subject to definitive agreements and due diligence.

KEY COMMERCIAL TERMS

1. Investment Amount. The Investor proposes to invest Rs. [Investment Amount] in the Company.

2. Pre-Money Valuation. The proposed pre-money valuation of the Company is Rs. [Pre-Money Valuation].

3. Securities. The investment shall be made by way of subscription to [Share Class] shares of the Company, issued in accordance with the Companies Act, 2013 and applicable FEMA/RBI regulations (if the Investor is a non-resident).

4. Board Composition. Following completion, the Investor shall be entitled to nominate [Board Seats for Investor] to the Company's Board of Directors.

5. Liquidation Preference. The Investor's shares shall carry a liquidation preference of [Liquidation Preference], payable in priority to other shareholders upon a liquidation event, sale, or winding up of the Company.

6. Conditions to Closing. Completion is subject to: [Key Closing Conditions], satisfactory legal and financial due diligence, and execution of definitive share subscription and shareholders' agreements.

7. Confidentiality. The parties agree to keep the terms of this Term Sheet, and all information exchanged in connection with the proposed investment, strictly confidential. This clause is legally binding.

8. Exclusivity. For a period of 45 days from the date of this Term Sheet, the Company agrees not to solicit, negotiate, or accept competing investment proposals. This clause is legally binding.

9. Governing Law. This Term Sheet (to the extent binding) shall be governed by the laws of the Republic of India. This clause is legally binding.

NON-BINDING NATURE

Except as expressly stated above, this Term Sheet does not constitute a legally binding commitment by either party and is intended solely as a basis for further negotiation and definitive documentation.

EXECUTION

Acknowledged as a basis for further negotiation by the parties below.
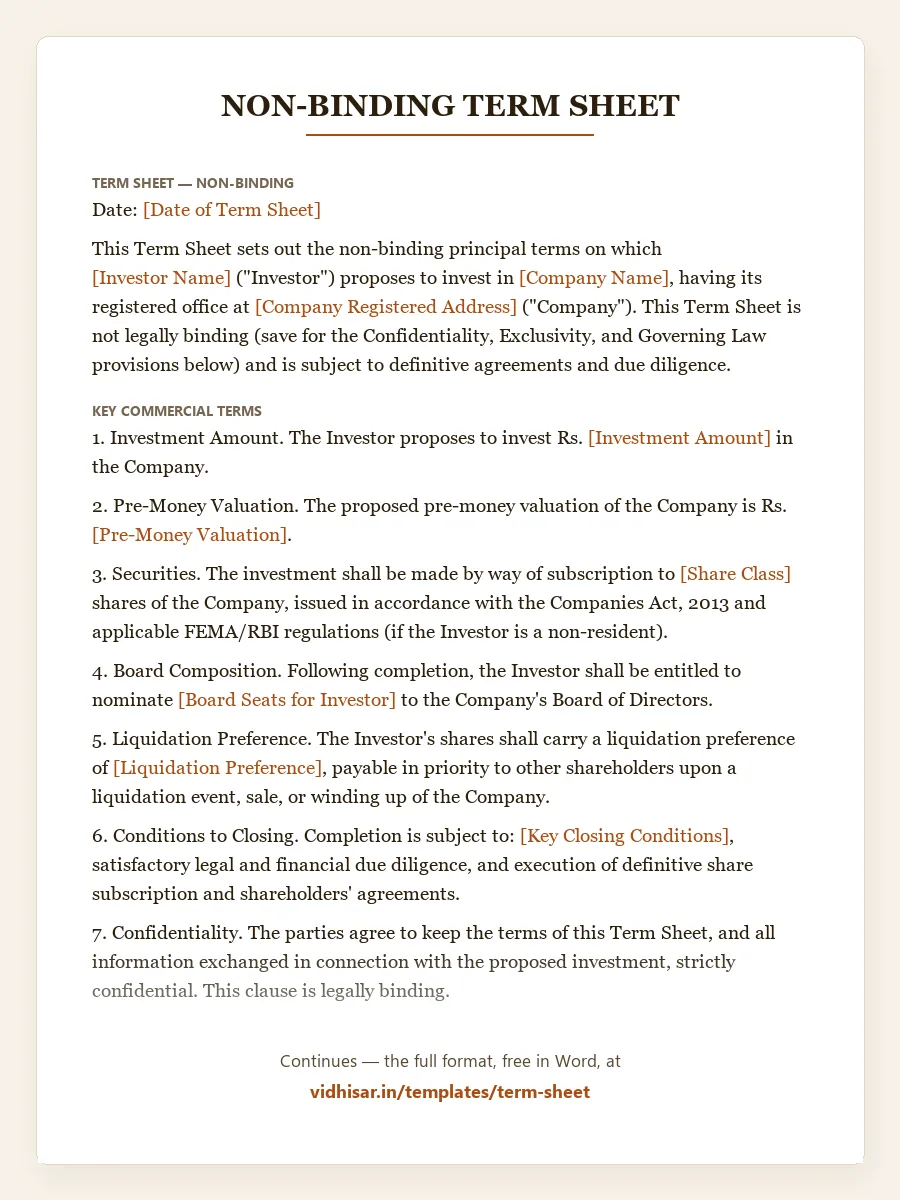
Non-Binding Term Sheet format (India): page one of the document, with each blank to fill in shown in brackets

Related statutory compliance tools & calculators

  • GST Late Fee Calculator 2026 — Calculate CGST/SGST Section 47 late fees and Section 50 interest
  • TDS Late Payment Interest Calculator — Calculate section 398 interest and section 427 late fees (formerly 201(1A) and 234E)

What this document must contain (Clause-by-Clause Matrix)

Non-Binding Term Sheet — Mandatory Clause Matrix & Statutory Protection (2026)
Essential Clause Legal Purpose & Protection Governing Law / Benchmark
Pre-money valuation and the amount raised State whether the option pool sits pre-money or post-money. That single word moves founder dilution materially and is the most common thing glossed over. Companies Act, 2013 — s. 62
Instrument and security type Equity shares, compulsorily convertible preference shares, or a convertible instrument — with conversion mechanics. Indian rounds commonly use CCPS, and the terms differ from ordinary equity. Foreign Exchange Management Act, 1999 and the rules made under it
Liquidation preference Whether it is participating or non-participating, and the multiple. This determines who gets what in a modest exit, which is the most likely exit. Indian Stamp Act, 1899
Board composition and reserved matters The reserved matters list is where real control sits. A minority investor with a long list of veto rights controls more than the shareholding suggests. Companies Act, 2013 — s. 62
Anti-dilution Broad-based weighted average, narrow-based, or full ratchet. The difference only shows up in a down round, when it matters most. Foreign Exchange Management Act, 1999 and the rules made under it
Founder vesting and lock-in Vesting schedule, cliff, and what happens on departure. Expect it; negotiate the terms rather than the principle. Indian Stamp Act, 1899
Which clauses are binding Confidentiality, exclusivity and costs typically bind even where the rest does not. Mark them explicitly so nobody is surprised. Companies Act, 2013 — s. 62
  • Pre-money valuation and the amount raised — State whether the option pool sits pre-money or post-money. That single word moves founder dilution materially and is the most common thing glossed over.
  • Instrument and security type — Equity shares, compulsorily convertible preference shares, or a convertible instrument — with conversion mechanics. Indian rounds commonly use CCPS, and the terms differ from ordinary equity.
  • Liquidation preference — Whether it is participating or non-participating, and the multiple. This determines who gets what in a modest exit, which is the most likely exit.
  • Board composition and reserved matters — The reserved matters list is where real control sits. A minority investor with a long list of veto rights controls more than the shareholding suggests.
  • Anti-dilution — Broad-based weighted average, narrow-based, or full ratchet. The difference only shows up in a down round, when it matters most.
  • Founder vesting and lock-in — Vesting schedule, cliff, and what happens on departure. Expect it; negotiate the terms rather than the principle.
  • Which clauses are binding — Confidentiality, exclusivity and costs typically bind even where the rest does not. Mark them explicitly so nobody is surprised.

When you need this

  • When an investor moves from interest to a concrete proposal
  • To fix the economics before legal costs are incurred on definitive documents
  • Where multiple investors are in the round and terms need to be consistent
  • Before granting exclusivity, which is a real commitment even in a non-binding document
  • To surface disagreement early, while it is still cheap to discover

The law that governs it

  • Companies Act, 2013 — s. 62 — Further issue of share capital must follow the procedure the section prescribes, including for a preferential allotment. The term sheet's structure has to be capable of being implemented through it.
  • Foreign Exchange Management Act, 1999 and the rules made under it — Where the investor is non-resident, pricing guidelines, permitted instruments and reporting requirements apply. Some structures common in other markets are not available on the same terms in India.
  • Indian Stamp Act, 1899 — Share issue and transfer attract stamp duty, and the definitive documents will need to be stamped. It is a cost worth anticipating at term sheet stage.

Common mistakes

  • Not clarifying whether the option pool is pre-money, which quietly shifts dilution onto the founders
  • Accepting a participating liquidation preference without modelling a modest exit
  • Treating the reserved matters list as boilerplate, when it is where control actually lives
  • Granting long exclusivity, which is binding and removes your leverage
  • Assuming structures common in US rounds transfer cleanly to an Indian company with a non-resident investor

Frequently asked questions

Is a term sheet legally binding in India?

Usually the commercial terms are expressed to be non-binding, while specific clauses — confidentiality, exclusivity or no-shop, and costs — are binding. What matters is what the document itself says, so the binding provisions should be identified expressly rather than inferred.

What is the difference between participating and non-participating liquidation preference?

A non-participating preference lets the investor take either their preference amount or their pro-rata share on conversion, whichever is greater. A participating preference lets them take the preference amount and then share in the remainder. The difference is largest in a modest exit, which is the most common kind.

Should the option pool be pre-money or post-money?

It is a negotiation, but the effect is not symmetric. A pre-money pool dilutes existing shareholders — the founders — before the investor comes in, so the same headline valuation delivers a materially different founder outcome depending on which is used.

What changes if the investor is a non-resident?

Foreign exchange regulation applies, covering permitted instruments, pricing guidelines and reporting. Some structures that are routine in other markets are treated differently in India, so the structure should be confirmed as implementable before the term sheet is signed rather than after.

Maintained by the VidhiSar Legal Team

Maintains the law explainers, calculators, templates and blog posts on vidhisar.in: checks them against the statute text and updates them when the law changes. Errors and changes in the law can be reported to legal@vidhisar.in.