Recovery · Template

Cheque bounce notice format — s. 138, Negotiable Instruments Act

A dishonoured cheque is the rare commercial dispute where the law hands you a criminal remedy — and takes it away again if you miss a date. Three clocks run: thirty days to send this notice, fifteen days the drawer then gets to pay, and one month after that to file. Miss the first one and the cheque is just paper.

Quick Statutory Answer

How long do I have to send a cheque bounce notice? Thirty days from the receipt of information from the bank that the cheque has been returned unpaid, under proviso (b) to s. 138. That is the date on your side of the transaction — not the date on the cheque and not the date you presented it — and missing it removes the criminal remedy for that dishonour.

Draft this document See all 30 templates

Cheque Bounce Notice (S. 138) format

The full text of this document as VidhiSar drafts it, with every blank shown in square brackets. Copy it or download it as a Word file and fill it in yourself — or answer a few questions and VidhiSar fills it in and prints a formatted PDF. Clauses that apply only in some cases are left out here; the drafting flow adds them when your answers call for them.

NOTICE DETAILS

Date: [Date of This Notice]

BY REGISTERED POST WITH ACKNOWLEDGEMENT DUE AND BY EMAIL

To, [Drawer's Name] [Drawer's Address]

From, [Your Name / Business Name] [Your Address]

Subject: Statutory notice of demand under Section 138 of the Negotiable Instruments Act, 1881 in respect of dishonour of cheque no. [Cheque Number] for Rs. [Cheque Amount]

BACKGROUND

1. Underlying Liability. You are liable to pay our client the sum stated below on account of [What the Money Was Owed For]. This liability is a legally enforceable debt subsisting on the date the cheque referred to below was drawn.

2. The Cheque. In discharge of that liability, you drew and delivered cheque no. [Cheque Number] dated [Date on the Cheque] for Rs. [Cheque Amount], drawn on [Drawer's Bank and Branch], in favour of [Your Name / Business Name].

3. Presentation. The said cheque was presented for encashment through [Your Bank] on [Date of Presentation], within the period of its validity.

4. Dishonour. The said cheque was returned unpaid, and we received the return memo of the bank dated [Date of Bank Return Memo] recording the reason for dishonour as "[Reason for Dishonour on the Memo]". This notice is issued within thirty (30) days of receipt of that information from the bank, as required by the proviso to Section 138 of the Negotiable Instruments Act, 1881.

DEMAND

5. Demand for Payment. You are hereby called upon to pay the sum of Rs. [Cheque Amount] to [Your Name / Business Name] within fifteen (15) days of receipt of this notice, by demand draft or by electronic transfer to the account notified to you.

6. Consequence of Non-Payment. Should you fail to make payment of the said amount within the said period of fifteen (15) days, our client shall be constrained to initiate criminal proceedings against you under Section 138 of the Negotiable Instruments Act, 1881, which is punishable with imprisonment for a term which may extend to two years, or with fine which may extend to twice the amount of the cheque, or with both. Such complaint shall be filed within one month of the date on which the cause of action arises under clause (c) of the proviso to Section 138, as provided by Section 142 of the said Act.

7. Interim Compensation. Your attention is drawn to Section 143A of the said Act, under which the court trying an offence under Section 138 may order the drawer to pay interim compensation of up to twenty per cent of the amount of the cheque, and to Section 148, under which an appellate court may require a deposit of a minimum of twenty per cent of the fine or compensation awarded.

8. Civil Remedies Reserved. Our client expressly reserves the right to recover the said amount together with interest and costs by way of civil proceedings, and the right to any other remedy available in law. Nothing in this notice shall be construed as a waiver of any such right.

9. Costs of This Notice. You shall additionally be liable for the costs of and incidental to this notice and to any proceedings arising out of it.

ACKNOWLEDGEMENT

A copy of this notice has been retained for record, along with proof of dispatch and the bank's return memo.

[Signatory Name] For and on behalf of [Your Name / Business Name]
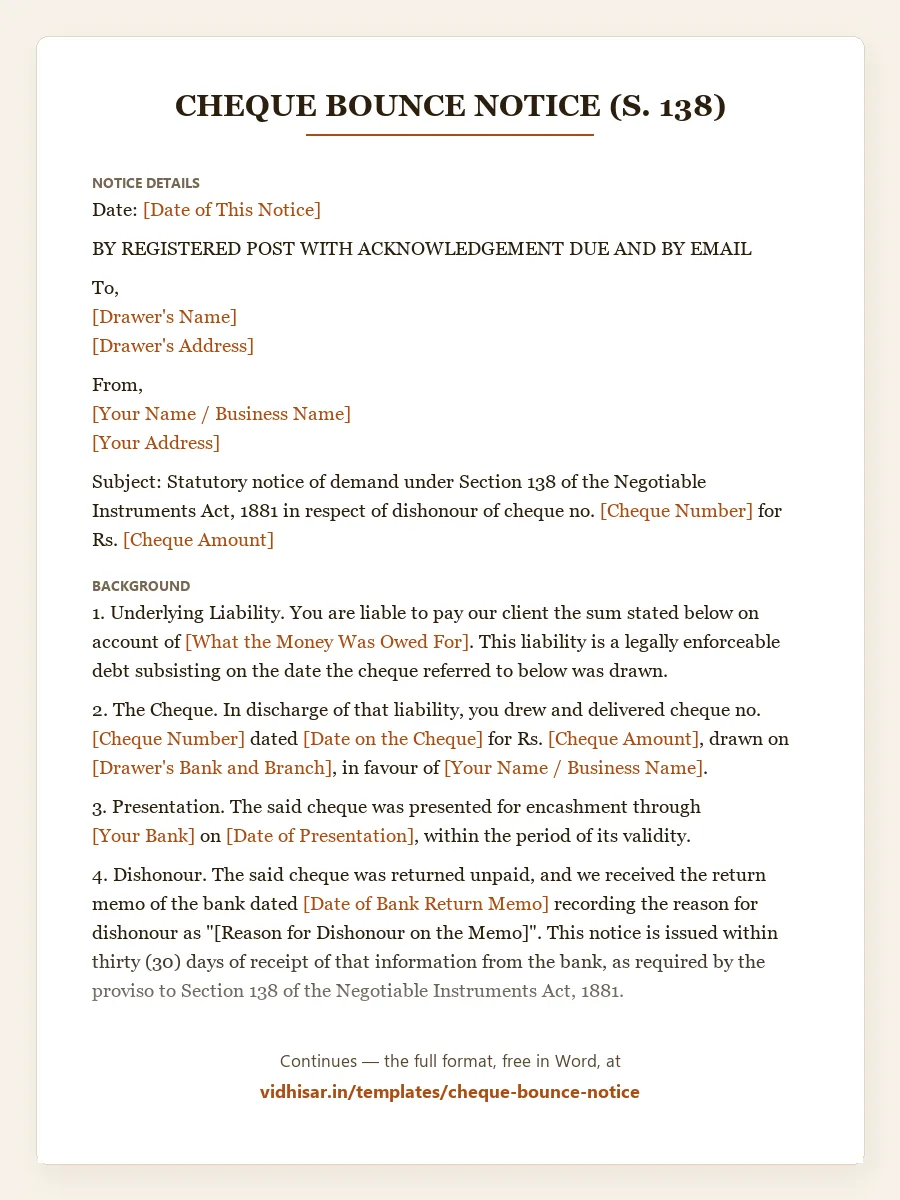
Cheque Bounce Notice (S. 138) format (India): page one of the document, with each blank to fill in shown in brackets

The provision behind this document

  • Section 138, Negotiable Instruments Act, 1881 — A criminal remedy on three deadlines: 30 days to demand, 15 for the drawer to pay, one month to file.

Further reading

What the law behind this document actually requires.

  • A cheque bounced. What section 138 actually gives you, and by when. — The Negotiable Instruments Act runs on three deadlines: 30 days, 15 days, one month. Miss any of them and the offence is gone, however good the debt.

Related statutory compliance tools & calculators

  • Cheque Bounce Deadline Calculator — Calculate statutory 30-day notice and 15-day payment window under Section 138

What this document must contain (Clause-by-Clause Matrix)

Cheque Bounce Notice (S. 138) — Mandatory Clause Matrix & Statutory Protection (2026)
Essential Clause Legal Purpose & Protection Governing Law / Benchmark
The underlying legally enforceable debt Section 138 protects a cheque issued in discharge of a debt or other liability. Say what the money was for. A cheque given as a gift, or against a liability that has ceased to be enforceable, does not attract the section. Negotiable Instruments Act, 1881 — s. 138
The full particulars of the cheque Number, date, amount and the bank it was drawn on. These are the facts the complaint will be built from, and an error here is repeated in every document that follows. Negotiable Instruments Act, 1881 — s. 142
The date of presentation, showing it was within validity A cheque presented after its validity period has expired does not give rise to the offence, so the notice should show on its face that presentation was in time. Negotiable Instruments Act, 1881 — ss. 143A and 148
The date you received the bank’s return memo, and the reason recorded on it This is the date the thirty-day clock runs from — not the date on the cheque, and not the date of presentation. It is the single most important date in the document. Negotiable Instruments Act, 1881 — s. 138
An unambiguous demand for the cheque amount, and fifteen days to pay it Demand the cheque amount clearly and on its own. Rolling interest, damages and legal costs into one composite figure has repeatedly been litigated as a failure to make a valid demand for the cheque amount, which is what the section requires. Negotiable Instruments Act, 1881 — s. 142
Service at the correct address, by a method that leaves proof Registered post with acknowledgement due to the drawer’s last known address, with the dispatch record kept. Service is a fact you will have to prove, and an undelivered notice sent to a stale address is a defence handed over free. Negotiable Instruments Act, 1881 — ss. 143A and 148
The consequence, stated plainly That a complaint under s. 138 will follow if payment is not made within the fifteen days. The notice is a demand with a stated consequence; leaving the consequence out weakens both its legal and its practical effect. Negotiable Instruments Act, 1881 — s. 138
  • The underlying legally enforceable debt — Section 138 protects a cheque issued in discharge of a debt or other liability. Say what the money was for. A cheque given as a gift, or against a liability that has ceased to be enforceable, does not attract the section.
  • The full particulars of the cheque — Number, date, amount and the bank it was drawn on. These are the facts the complaint will be built from, and an error here is repeated in every document that follows.
  • The date of presentation, showing it was within validity — A cheque presented after its validity period has expired does not give rise to the offence, so the notice should show on its face that presentation was in time.
  • The date you received the bank’s return memo, and the reason recorded on it — This is the date the thirty-day clock runs from — not the date on the cheque, and not the date of presentation. It is the single most important date in the document.
  • An unambiguous demand for the cheque amount, and fifteen days to pay it — Demand the cheque amount clearly and on its own. Rolling interest, damages and legal costs into one composite figure has repeatedly been litigated as a failure to make a valid demand for the cheque amount, which is what the section requires.
  • Service at the correct address, by a method that leaves proof — Registered post with acknowledgement due to the drawer’s last known address, with the dispatch record kept. Service is a fact you will have to prove, and an undelivered notice sent to a stale address is a defence handed over free.
  • The consequence, stated plainly — That a complaint under s. 138 will follow if payment is not made within the fifteen days. The notice is a demand with a stated consequence; leaving the consequence out weakens both its legal and its practical effect.

When you need this

  • When a cheque given to you has been returned unpaid — insufficient funds, payment stopped, account closed
  • Within thirty days of the bank informing you of the return, which is the window that decides whether s. 138 stays available at all
  • When a customer paid an invoice by cheque and the cheque has bounced
  • When a security cheque given against a loan or an advance has been dishonoured
  • Before filing any complaint — this notice is a precondition to the offence, not an optional opening move

The law that governs it

  • Negotiable Instruments Act, 1881 — s. 138 — Dishonour of a cheque for insufficiency of funds is an offence punishable with imprisonment which may extend to two years, or a fine which may extend to twice the amount of the cheque, or both. The provisos make it conditional: presentation within the period of validity, a written demand made within thirty days of receiving information of the dishonour from the bank, and failure by the drawer to pay within fifteen days of receiving that demand.
  • Negotiable Instruments Act, 1881 — s. 142 — The complaint must be in writing, made by the payee or the holder in due course, and filed within one month of the date on which the cause of action arises under clause (c) of the proviso to s. 138 — that is, once the fifteen days have run out. A court may take cognizance of a late complaint where sufficient cause for the delay is shown.
  • Negotiable Instruments Act, 1881 — ss. 143A and 148 — The trial court may direct the drawer to pay the complainant interim compensation of up to twenty per cent of the cheque amount, and an appellate court may require a deposit of at least twenty per cent of the amount awarded. This is why a s. 138 proceeding moves money in a way an ordinary civil recovery suit does not.

Common mistakes

  • Counting the thirty days from the date on the cheque, or from the date of presentation, instead of from the day the bank informed you of the dishonour
  • Sending the notice by ordinary post or over WhatsApp alone, leaving no proof of service to produce later
  • Demanding the cheque amount, interest, damages and legal costs as one lump sum, which invites the argument that no valid demand for the cheque amount was ever made
  • Losing track of which dishonour the notice and the complaint are actually built on, after presenting the same cheque more than once
  • Letting the one-month filing window lapse while waiting to see whether payment turns up

Frequently asked questions

How long do I have to send a cheque bounce notice?

Thirty days from the receipt of information from the bank that the cheque has been returned unpaid, under proviso (b) to s. 138. That is the date on your side of the transaction — not the date on the cheque and not the date you presented it — and missing it removes the criminal remedy for that dishonour.

What happens if the drawer pays within the fifteen days?

Then the offence is not complete and no complaint lies. Payment within the statutory window is a complete answer to a s. 138 case, which is exactly what the notice period is for — it gives the drawer a final chance and gives you a clean record of having offered it.

Can I file a civil suit for the money as well?

Yes. The s. 138 proceeding is criminal and results in a fine or compensation; recovering the debt itself through a civil suit is a separate remedy with its own limitation period. Reserve the civil remedy expressly in the notice so nothing you write is read as giving it up.

The cheque was only given as security — does s. 138 still apply?

It turns on whether a legally enforceable debt or liability existed when the cheque was presented. A security cheque backing a live liability is generally within the section; one given against a liability that never arose, or that had already ceased to be enforceable, is contested ground and is decided on the facts of the transaction.

Maintained by the VidhiSar Legal Team

Maintains the law explainers, calculators, templates and blog posts on vidhisar.in: checks them against the statute text and updates them when the law changes. Errors and changes in the law can be reported to legal@vidhisar.in.